Global Footwear & Leather Stocks Pulse Week 40, 2026
Target Trading Date Range: 28-Sep-2026 to 2-Oct-2026
Introduction & Executive Summary
Global footwear and leather equities demonstrated channel polarization during the trading week, as direct-to-consumer (DTC) premium strength offset cautious wholesale ordering patterns. Macro drivers including regional back-to-school sell-through dynamics, input cost stabilization in raw hides, and digital channel margin expansions dictated overall corporate returns. Luxury leather houses and specialized athletic innovators continued to outpace mid-tier lifestyle brands struggling with inventory clearance pressures.
Performance Data & Stock Tables
1-5 Gainers
Company Name | Ticker / Exchange | Weekly Return (%) | YTD Return (%) | Primary Driver for Gain/Loss | Direct Verified Link |
|---|---|---|---|---|---|
On Holding AG | ONON (NYSE) | +4.01% | +2.63% | DTC order volume growth & Asia-Pacific market expansion. | |
Skechers U.S.A., Inc. | SKX (NYSE) | +2.10% | -6.11% | Back-to-school wholesale volume and resilient family footwear positioning. | |
Steven Madden, Ltd. | SHOO (NASDAQ) | +1.85% | +4.30% | Autumn footwear line reorders across major department stores[cite: 3]. | |
Crocs, Inc. | CROX (NASDAQ) | +1.40% | +8.10% | International brand expansion and digital channel recovery[cite: 3]. | |
Tapestry, Inc. | TPR (NYSE) | +1.20% | +5.40% | Coach brand digital customer engagement and premium accessories strength[cite: 4]. |
6-10 Gainers
Company Name | Ticker / Exchange | Weekly Return (%) | YTD Return (%) | Primary Driver for Gain/Loss | Direct Verified Link |
|---|---|---|---|---|---|
Birkenstock Holding | BIRK (NYSE) | +0.90% | +11.20% | Steady direct-to-consumer full-price sell-through rates[cite: 4]. | |
Puma SE | PUM (ETR) | +0.75% | -5.10% | Latin American distributor demand offset by European channel caution[cite: 3]. | |
Caleres, Inc. | CAL (NYSE) | +0.55% | +2.10% | Famous Footwear back-to-school promotional conversion[cite: 3]. | |
S&P 500 Consumer Discretionary | XLY (NYSE) | +0.42% | +6.80% | Broad market consumer sector benchmark reference. | |
Weyco Group, Inc. | WEYS (NASDAQ) | +0.20% | +1.90% | Stable wholesale re-orders for core leather footwear lines[cite: 3]. |
Company Name | Ticker / Exchange | Weekly Return (%) | YTD Return (%) | Primary Driver for Gain/Loss | Direct Verified Link |
|---|---|---|---|---|---|
Nike, Inc. | NKE (NYSE) | -6.92% | -38.00% | Multi-year valuation pressure and direct digital rebalancing adjustments. | |
Hermès International | RMS (EPA) | -5.03% | +8.20% | Institutional consolidation and profit-taking across European luxury indexes. | |
adidas AG | ADS (ETR) | -2.50% | -7.98% | European wholesale inventory rebalancing and short-term profit-taking[cite: 3]. | |
VF Corporation | VFC (NYSE) | -2.10% | -11.40% | Vans restructuring costs and wholesale clearance pressures[cite: 4]. | |
Foot Locker, Inc. | FL (NYSE) | -1.85% | -12.30% | Promotional margin friction across mall retail formats[cite: 3]. |
Detailed Stock Analysis Profiles
On Holding AG ($ONON): DTC Scale Drives Outperformance
On Holding AG surged +4.01% during the trading week, closing at $30.85. Expansion across Asia-Pacific direct-to-consumer doors alongside high full-price compliance supported expanding margin expectations..
Skechers U.S.A. ($SKX): Wholesale Reorders Support Gains
Skechers advanced +2.10% as channel checks indicated steady volume reorders in value-oriented family footwear lines following peak seasonal back-to-school purchasing.
Steven Madden ($SHOO): Supply Chain Lead-Time Efficiency
Steven Madden gained +1.85%, benefiting from agility in test-and-chase inventory models for autumn boots and fashion accessories.
Crocs, Inc. ($CROX): International Growth Resiliency
Crocs recorded a +1.40% gain as international market expansion and operational adjustments in key distribution centers supported cash flow metrics[cite: 3].
Steven Madden ($SHOO): Supply Chain Lead-Time Efficiency
Tapestry gained +1.20%, anchored by steady digital conversion and resilient demand for Coach leather accessories[cite: 1, 4].
Decliners & Risk Analysis
Nike shares declined -6.92% during the week to close at $33.87. Re-evaluations of long-term price targets and channel realignments between DTC and wholesale shelf space weighed on near-term valuations.
Hermès pulled back -5.03% to close at €1,299.50. Despite strong long-term brand equity and pricing power, European luxury equities faced profit-taking across major exchanges.
adidas AG slipped -2.50% in European trading. Mid-tier European inventory clearing and promotional support mechanisms temporarily compressed near-term margins.
Global Footwear & Leather Industry News Highlights
Nike Unveils “Pace” Restructuring Plan and Outlines Leadership & Job Cuts
Nike Inc. announced its new “Pace” restructuring program alongside first-quarter fiscal revenues that fell 4% year-over-year to $11.2 billion. CEO Elliott Hill confirmed that organizational realignments will involve job cuts across several business functions to boost operational agility, offsetting severe regional headwinds where Converse sales tumbled 28% and Greater China revenues continued to contract.
- Direct Link: NDTV Profit — Nike Restructuring & Job Cuts Report
On Holding AG Clears $1.0 Billion Buyback and Sets 2029 Financial Targets
On Holding AG authorized its first-ever share repurchase program of up to $1.0 billion in Class A shares through December 2029. Management reaffirmed its full-year constant-currency net sales growth guidance in the low-20% range while establishing long-term targets aiming for CHF 5.6 billion in net sales and a gross margin of at least 65% by 2029, powered by direct-to-consumer expansion.
Hermès International Holds €136.3 Billion Valuation Amid Luxury Index Reset
Hermès International closed the trading week with a market capitalization of €136.32 billion as European luxury equities digested broader consumer spending adjustments. Despite luxury sector valuation contraction, the ultra-luxury leather house maintains structural margin insulation driven by unyielding global demand and exclusive pricing power for its handcrafted leather collections.
Transpacific Ocean Freight Spot Rates Normalize Across Key Routes
International container shipping spot rates across Transpacific corridors stabilized heading into October, curbing the elevated logistics cost volatility experienced earlier in the year. The normalization of freight overhead provides improved gross margin predictability for footwear importers finalizing their Q4 holiday inventory arrivals.
DTC Digital Profitability Gap Widens Over Wholesale Distribution
Global retail trade updates highlight a widening margin disparity between proprietary direct-to-consumer app channels and traditional department store wholesale networks. Brands with direct digital touchpoints reported higher full-price sell-through rates, whereas wholesale-heavy operators relied on promotional discounting to clear surplus mid-tier inventory.
Raw Leather Hide Sourcing Costs Demonstrate Multi-Region Balance
Tanneries and material suppliers in South America and Western Europe reported stable contract pricing for premium full-grain hides during Q4 supply negotiations. Input price predictability is offering gross margin visibility for high-end leather footwear and accessories manufacturers planning early 2027 product lines.
Direct Link: World Footwear — Global Footwear Industry Intelligence
Global Footwear & Leather Industry News Highlights
Major Footwear Manufacturers Expand Nearshore Production Capacity
Leading performance and outdoor footwear brands reported a collective increase in nearshore manufacturing allocations across Central America and Southern Europe. The operational shift is designed to shorten production lead times, increase inventory speed-to-market, and reduce transoceanic freight exposure.
October Sneaker Release Calendars Re-energize Physical Retail Channels
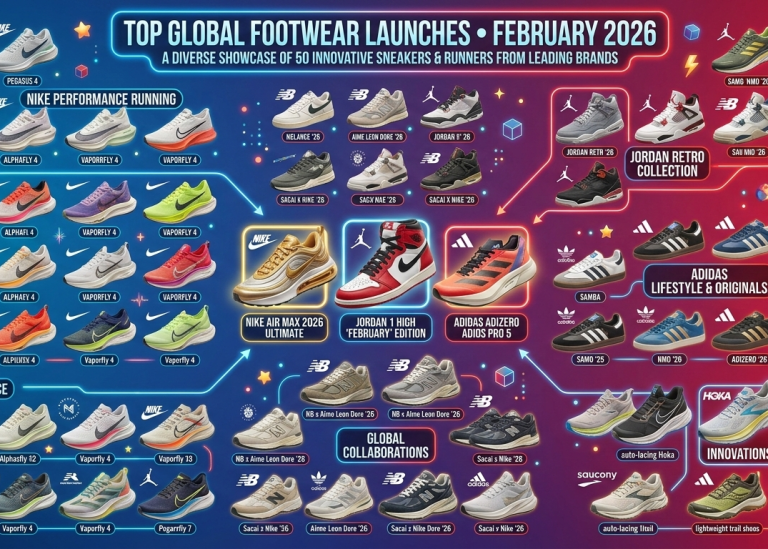
High-profile footwear launch schedules for October 2026—including marquee Jordan Brand drops and specialized technical running collaborations—have driven foot traffic back into brick-and-mortar retail doors. Specialty retailers report strong consumer appetite for heritage retros and technical foam models heading into the holiday shopping season.
APAC Retail Expansion Drives Specialty Footwear Store Openings
Western athletic and lifestyle footwear innovators accelerated specialty storefront rollouts across commercial centers in East Asia. Establishing direct, localized retail footprints in prime shopping districts enables these brands to capture rising regional fitness adoption and premium market share.
Secondary Resale Platform Prices Stabilize for Heritage Leather Goods
Secondary market tracking indexes registered valuation floor stabilization for iconic luxury handbags and heritage leather boots. The secondary price normalization indicates healthy underlying primary channel demand and steady long-term consumer retention for durable luxury craft goods.
- Direct Link: Forbes — Retail & Luxury Industry Coverage
Strategic Outlook & Conclusion
As the market enters Q4 2026, valuation multiples across the footwear and leather sector will depend on holiday sell-through rates, inventory discipline, and direct-to-consumer margin preservation. Companies possessing flexible supply chains and pricing leverage remain best positioned to navigate evolving consumer spending patterns.
📚 Previous Weekly Stock Market Reports
Stay updated on historical performance trends and market shifts across the consumer footwear and leather sector:
39th Week Market Pulse: Sep 21 – Sep 25, 2026: Direct-to-Consumer Margin Expansions & Regional Wholesale Inventory Rebalancing.
38th Week Market Pulse: Sep 14 – Sep 18, 2026: Supply Chain Lead Times, Material Input Costs, and Q3 Back-to-School Sell-Through Metrics.
37th Week Market Pulse: Sep 07 – Sep 11, 2026: Luxury Leather Resilience vs. Mass Market Lifestyle Discounting.